Calculate UK Glass Bottle Landed Cost After Anti Dumping Measures
Release time: 2026-10-01
Prepared 16 September 2026. Check current official guidance before relying on this article for a shipment.
Separate exposure from permanent cost
A purchasing budget should distinguish the product invoice, customs valuation, normal import charges and provisional anti-dumping exposure. This makes it easier to compare commercial scenarios without implying that every secured amount is already a final tax expense.
Under the current provisional notice, importers provide a guarantee using a bank guarantee, bond or cash; the guaranteed amount becomes payable only if definitive measures are imposed. The notice also explains collection and reimbursement treatment.
Use a consistent calculation base
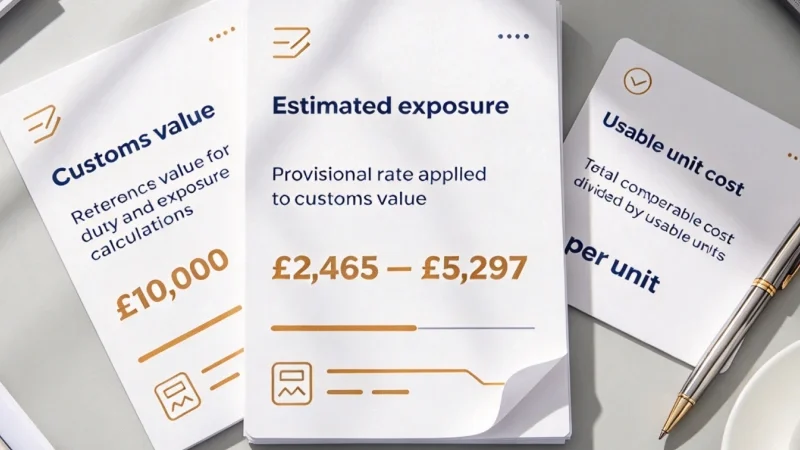
For the simplified comparison below, estimated anti-dumping exposure equals customs value multiplied by the applicable provisional rate. Customs value should be established separately with the broker; it should not automatically be equated with the factory invoice.
The figures compare only this exposure. They are not total landed-cost quotations and exclude ordinary duty, VAT, financing charges, brokerage and delivery costs.
| Customs value | 24.65% | 25.88% | 26.87% | 52.97% |
| £10,000 | £2,465.00 | £2,588.00 | £2,687.00 | £5,297.00 |
| £20,000 | £4,930.00 | £5,176.00 | £5,374.00 | £10,594.00 |
| £50,000 | £12,325.00 | £12,940.00 | £13,435.00 | £26,485.00 |
Add the costs outside the illustration
Build separate lines for bottles, closures, decoration, tooling allocation, freight, insurance, clearance, local delivery and quality control. Identify amounts already included in customs value to avoid counting them twice.
Show VAT and its potential recovery separately with input from your tax adviser. Do not assume that VAT is fully recoverable or that it is always a permanent product cost.
Divide by usable units
Suppose two hypothetical shipments each contain 20,000 bottles. If one leaves 19,800 usable bottles and the other 19,200, the denominator changes even when the invoice quantity is identical. Divide the comparable total by usable units rather than purchased units.
Estimate breakage and rejection from relevant evidence. Do not present an assumed loss percentage as a forecast for every supplier or shipment.
Make the budget decision ready
Use a base scenario, a documentation risk scenario and a freight sensitivity scenario. Put an owner and a review date beside each assumption.
A lower factory price can be outweighed by poor packing, unexpected tooling costs or an unsupported rate assumption. A well-structured costing sheet shows which factor creates the difference and which evidence would resolve it.
elated guides
UK Glass Bottle Anti Dumping Rates Explained
Discuss your packaging project with Gowing
Send a bottle photo or drawing, capacity, intended use, quantity and delivery target. These details help structure a discussion of the specification, manufacturing information and quotation requirements.
Contact Gowing about a UK glass packaging project
Explore Gowing glass packaging
Sources and scope
UK Government current glass container trade remedies notice
General procurement information. Shipment classification, customs and tax treatment require product-specific review by the importer and its advisers. Calculations and scenarios are illustrative.